Before You Book the Banquet Hall: The Real Math of a $75K Desi Wedding
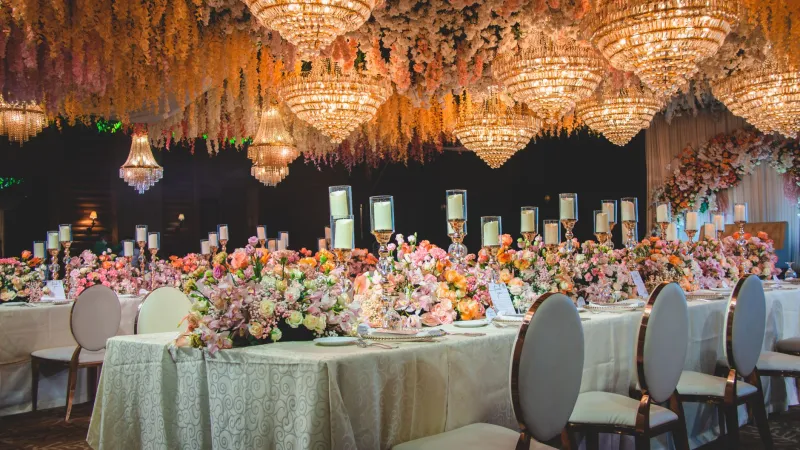
Let's just say it out loud: the average South Asian wedding in the US routinely runs $50,000 to $100,000. Event planners put multi-day celebrations in New Jersey, Texas, and California well past the $75K mark once you add the venue, the caterer, the outfits, the photographer, and the second (and third) outfit changes.
Nobody's here to tell you to elope. Weddings matter — they're family, community, and culture rolled into one weekend. But there's a difference between spending big and starting your marriage in a financial hole. So let's run the actual numbers.
Where the Money Actually Goes
A typical $75K budget breaks down roughly like this:
- Venue and catering: $35,000–$45,000 (per-plate costs of $100–$150 add up fast at 250 guests)
- Photography and video: $6,000–$10,000
- Attire and jewelry: $5,000–$8,000
- Decor and florals: $8,000–$12,000
- Mehndi, sangeet, and reception extras: $5,000–$8,000
Notice something? The guest list is the single biggest cost driver. Every table of ten is $1,000–$1,500. Trimming 50 guests saves more than any negotiation with the DJ ever will.
The Financing Traps Nobody Warns You About
The 401(k) Loan
Borrowing from your 401(k) feels like free money — you're paying yourself back, right? Wrong. If you leave or lose your job, the loan typically becomes due within weeks, and any unpaid balance is treated as a withdrawal with taxes and penalties. Worse, the money you pull out stops compounding during your highest-growth decades. A $30K loan at age 28 could cost you six figures in lost retirement growth.
Points Hacking Gone Wrong
Yes, putting wedding expenses on a new rewards card to chase a sign-up bonus can work. It works for people who pay the balance in full every month. It does not work when the caterer's final invoice pushes you past 30% utilization and you're carrying $20K at 24% APR. One year of interest on that wipes out every point you earned, twice over.
Raiding the Down Payment Fund
This is the quiet one. Couples who've saved $60K for a house 'borrow' $25K for the wedding, promising to replace it. Then life happens — and five years later they're still renting, wondering where the decade went. Your wedding is one weekend. Your housing situation is every day.
A Framework That Actually Works
1. Set the ceiling before the planning starts. Decide the total number — with both sets of parents in the room — and treat it as non-negotiable. Venue choice flows from the budget, not the other way around.
2. Cap the guest list at what the budget supports. Rough rule of thumb: venue + catering should be under 60% of your total, and the guest list should be whatever that number buys.
3. Fund it from three sources only: current savings, cash flow during the engagement (12–18 months of aggressive saving), and family contributions actually offered, not extracted.
4. Zero high-interest debt. If the only way to close the gap is a credit card, the event is too big. Full stop.
5. Protect your other goals. Retirement contributions and the emergency fund don't pause for the baraat. If you can't keep both running and pay for the wedding, scale the wedding down.
Celebrate Loud, Start Clean
The best weddings I've seen weren't the most expensive ones — they were the ones where the couple started married life with savings intact, no debt, and no resentment about money. Your aunties will talk about the floral arrangements for a month. Your bank statements follow you for years. Choose accordingly.