Respectfully, Beta — Your Parents' Money Rules Don't Work Here Anymore
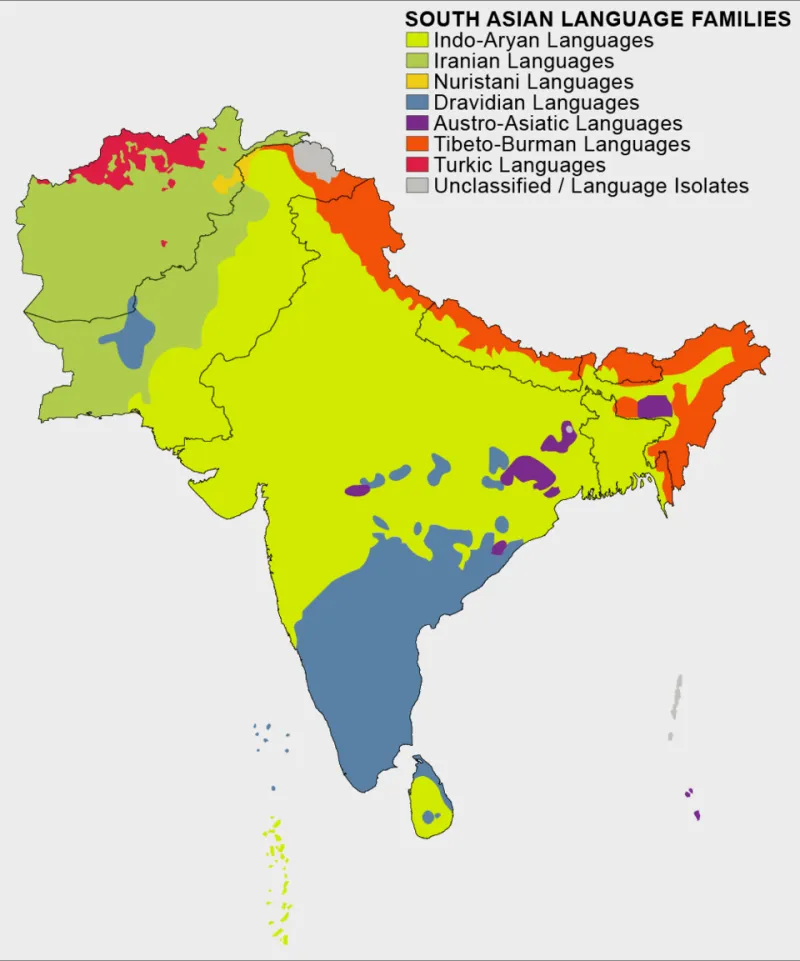
Photo: Afrogindahood, CC0, via Wikimedia Commons
Let me say this clearly upfront: your parents are not wrong for what they believe about money. They survived economic instability, currency devaluations, and systems that genuinely couldn't be trusted. The financial instincts they developed were calibrated for real threats. Those instincts kept families fed, kids educated, and futures protected.
But here's the thing about survival instincts — they're optimized for the environment that created them. And you are operating in a fundamentally different environment.
The Three Big Ones: Cash, Property, and "Don't Trust the Market"
Most of what I hear from second-gen South Asian readers boils down to three inherited financial beliefs that need serious examination.
Cash is king, always. The idea of keeping significant money in savings accounts or physical cash — accessible, visible, controllable — is deeply embedded in South Asian financial culture. It makes sense when you come from places where banking systems were unreliable or governments could freeze accounts overnight. In the US, with FDIC insurance, market access, and inflation running at 3-4% annually, cash hoarding isn't safety. It's a slow leak. Keeping two to three years of expenses liquid is smart. Keeping eight years of income in a high-yield savings account because it "feels safe" is costing you compounding returns you'll never get back.
Real estate is the only real investment. This one's particularly loaded for South Asian families because it's tangled up in status, legacy, and identity. Owning property — here, back home, ideally both — is the marker of having made it. And yes, real estate can be a genuinely excellent investment. But the version many Desi parents push involves buying plots in Indian cities they'll never live in, or over-concentrating net worth in a single illiquid asset class because "land never goes to zero." Meanwhile, a diversified portfolio of index funds has quietly done 10-12% annually over long periods. Property in Hyderabad has done... well, it depends heavily on which neighborhood, which decade, and whether you can actually get the title sorted.
The stock market is gambling. This belief is the one that probably costs South Asian families the most cumulative wealth of anything on this list. The stock market, to a generation that watched neighbors lose everything in speculative investments or heard stories of brokers disappearing with client funds, looks like a casino. But a low-cost index fund tracking the S&P 500 is not a hot stock tip. It's ownership in the five hundred largest American companies, diversified automatically, with costs near zero. Confusing this with gambling is like confusing a savings account with keeping cash under a mattress — technically the same category, completely different risk profile.
Why This Advice Persists Even When It Doesn't Fit
Here's what makes this complicated: the advice isn't random. It's deeply rational given the context it came from. And it's delivered with love, which makes it harder to push back on without feeling like you're rejecting the people who sacrificed to give you options.
There's also a generational authority dynamic that runs deep in South Asian households. Money conversations aren't really conversations — they're guidance delivered by people who've earned the right to give it. Disagreeing feels disrespectful, and in many families, it gets read that way.
But respecting someone's wisdom doesn't require adopting their framework wholesale. You can honor where your parents came from while also doing the math on where you actually are.
The Wealth Gap This Creates
Let's put some numbers to this. A 30-year-old who invests $1,000 a month in a diversified index portfolio and earns a historical average of 10% annually will have roughly $2.3 million by 65. A 30-year-old who keeps that same $1,000 a month in a high-yield savings account at 4.5% — considered excellent by traditional standards — will have around $900,000. That's a $1.4 million gap, created entirely by philosophy, not income.
Multiply that across a household with two earners following traditional Desi money logic, and you're looking at a generational wealth difference that compounds forward into your kids' lives and their kids' lives. This is not abstract. This is real money that either gets built or doesn't.
Charting a Different Course Without Burning the House Down
The goal isn't to dismiss your parents. It's to update the operating system while keeping the values that actually matter — discipline, delayed gratification, family orientation, long-term thinking. Those are genuinely excellent financial virtues. The specific vehicles they get applied to just need to evolve.
A few things that have worked for readers navigating this:
Reframe, don't debate. Instead of arguing that index funds are better than gold, talk about how you're "diversifying the way American institutions do." Language matters. "I'm investing like the university endowments" lands differently than "I'm putting money in the stock market."
Show the math quietly over time. When your Roth IRA grows 40% over three years while the plot in Pune sits unsold, you don't need to make a speech. The numbers speak. Let them.
Establish your own financial decisions as a boundary, not a battleground. "I hear you, and I'm making a different choice for my situation" is a complete sentence. You can listen to advice without implementing it, and you don't owe anyone a debate about your own retirement account allocation.
Find the overlap. Your parents care about security, legacy, and not being a burden. So do you. Build your financial plan around those shared values, using different tools. When they see the outcomes align with what they actually care about, the method becomes less important.
The Respect Argument Goes Both Ways
Here's my honest take: the most respectful thing you can do for your parents' sacrifice is to actually build the wealth they were trying to create for you. If their advice, applied literally in your context, produces worse outcomes than alternative strategies would, following it out of deference isn't respect — it's a missed opportunity dressed up as tradition.
They worked this hard so you'd have choices. Use them.